Category: Uncategorized

  • 7 Mistakes You’re Making with Your 2026 Miami Roof Estimate (and How to Fix Them)

    7 Mistakes You’re Making with Your 2026 Miami Roof Estimate (and How to Fix Them)

    Getting a roof estimate in Miami isn't what it used to be. As we move into 2026, the combination of stricter building codes, rising material costs, and a tightening insurance market has turned a "simple quote" into a complex financial decision. In Miami-Dade County, your roof isn't just a cover for your home; it’s a high-performance system designed to survive 175-mph winds and six months of torrential rain.

    If you’re looking at a roof replacement in Miami this year, you’re likely seeing numbers between $10,000 and $28,000 for standard shingles, and upwards of $45,000 for premium metal or tile systems. But the price tag is only half the story. Most homeowners are making critical errors during the estimation phase that lead to failed inspections, denied insurance claims, and thousands in "hidden" costs later on.

    Here are the seven most common mistakes Miami homeowners make with their 2026 roof estimates, and exactly how you can avoid them.

    1. Ignoring HVHZ and NOA Requirements

    Miami-Dade is the heart of the High Velocity Hurricane Zone (HVHZ). This isn't just a label; it’s a legal designation that mandates the strictest roofing standards in the United States.

    A common mistake is accepting a "general" estimate that uses standard Florida building materials. In Miami, every single component of your roof, from the shingles and tiles to the nails and underlayment, must have a Miami-Dade Notice of Acceptance (NOA).

    The Fix: When you get an estimate, demand to see the NOA numbers for the specific products the contractor plans to use. If a roofer tells you "Florida Product Approval" is enough, they aren't qualified for Miami work. Using non-NOA materials can lead to a failed final inspection, meaning you might have to tear the whole thing off and start over.

    2. Choosing the Lowest Bid Without a Detailed Scope

    In a high-demand market like Miami, "budget" contractors often lure homeowners with low-ball estimates. These estimates are usually vague, missing critical details like decking replacement costs or flashing upgrades.

    • Budget Tier ($10,000 – $14,000): Often covers 3-tab shingles and basic felt underlayment (Risky).
    • Popular Tier ($17,000 – $22,000): Typically includes architectural shingles, high-quality underlayment, and all permits (Standard).
    • Premium Tier ($28,000+): Covers designer shingles, metal, or concrete tile with advanced warranties (Best Protection).

    The Fix: Never sign a contract that simply says "Replace Roof." Your estimate should be an itemized list including tear-off, disposal, underlayment type, drip edge, flashing, and a "per-sheet" price for plywood decking repairs. At Get My Roof Estimate Now, we provide transparent pricing breakdowns so you know exactly where your money is going before a contractor ever steps foot on your property.

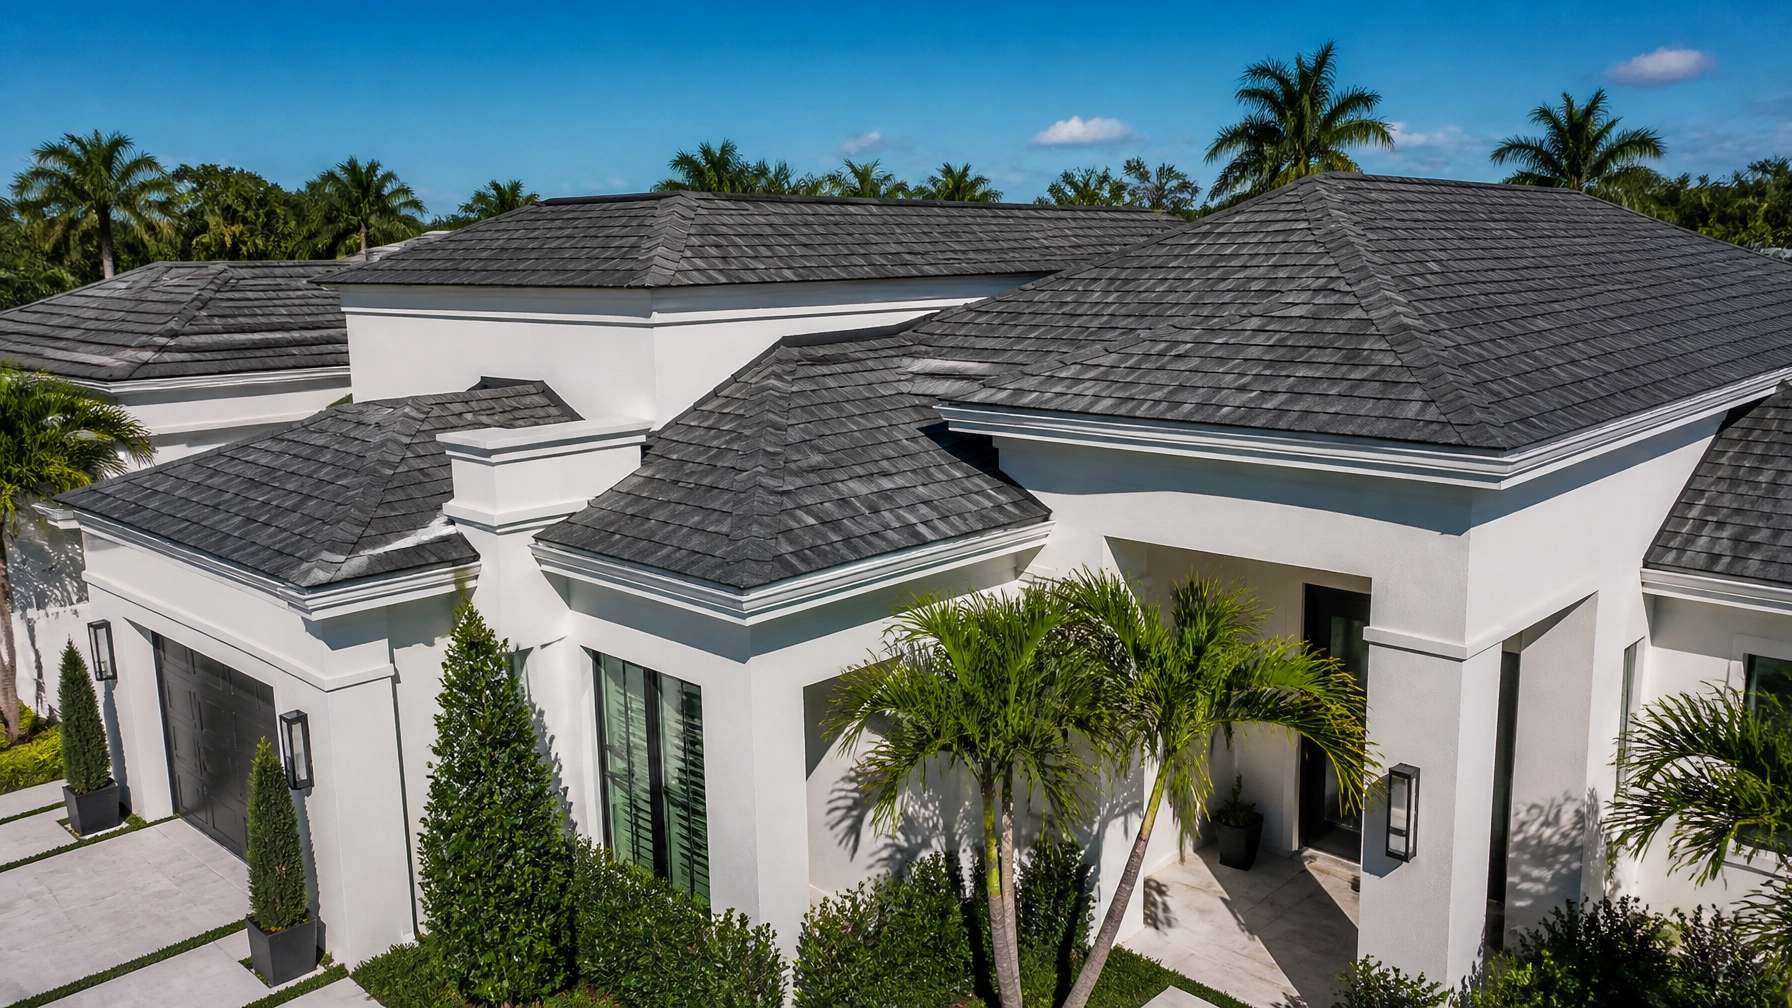
    Mediterranean-style Miami home with a fresh terracotta tile roof

    3. Letting the Contractor Skip the Permit

    With the 2026 backlog of construction in South Florida, some contractors may suggest "saving time" by starting without a permit or asking you, the homeowner, to pull the permit. This is a massive red flag.

    If you pull the permit, you are legally responsible for the work. If the contractor skips the permit entirely, you have no official record of the roof's age or code compliance. This will come back to haunt you when you try to sell your home or renew your insurance.

    The Fix: The contractor must always pull the permit. It ensures that city inspectors will visit your home to verify that the roof meets HVHZ standards. No permit means no proof of protection.

    4. Overlooking the "Secondary Water Barrier"

    In Miami, it’s not a matter of if a hurricane hits, but when. The 2026 Florida Building Code places a heavy emphasis on the Secondary Water Barrier (SWB). This is a self-adhered underlayment that sticks directly to the wood deck. If your shingles blow off during a storm, the SWB is the only thing keeping your house dry.

    Many estimates skip this or use cheaper "staple-down" felt to keep the price low.

    The Fix: Ensure your estimate specifically mentions "self-adhered underlayment" or "peel-and-stick." While it adds about $1,000 to $2,500 to the total cost, it can save you tens of thousands in interior water damage and significantly lower your insurance premiums.

    Modern Miami house featuring a sleek standing-seam metal roof

    5. Misunderstanding the "25% Rule"

    Many Miami homeowners try to save money by doing a large repair instead of a full replacement. However, Florida law (the 25% Rule) states that if you repair more than 25% of a roof area within a 12-month period, the entire roof must be brought up to current code.

    The Fix: If your roof is over 15 years old and has significant damage, a partial repair is often a waste of money. Most insurance companies in 2026 won't even renew policies for asphalt roofs older than 15 years in South Florida. Use our Roof Cost Calculator to see if a full replacement fits your budget better than a series of expensive patches.

    6. Waiting Until a Leak Occurs

    The worst time to get a roof estimate is when water is dripping into your living room. In Miami’s rainy season, roofing crews are booked weeks in advance. Emergency repairs and "rush" replacements come with a 20-30% price premium.

    Furthermore, a leaking roof often means the wood decking underneath is rotting. What started as a $15,000 shingle job can quickly turn into a $20,000 job once the "hidden" wood damage is uncovered.

    The Fix: Be proactive. If your roof is nearing the end of its lifespan (15-20 years for shingles, 25-30 for tile), get an estimate now. Our satellite technology allows you to get an accurate pricing range in under 60 seconds without the pressure of a salesperson sitting at your kitchen table.

    Clean architectural shingle roof on a classic Miami ranch home

    7. Failing to Get a Wind Mitigation Inspection

    The biggest mistake happens after the roof is finished. Most Miami homeowners forget to order a new Wind Mitigation Inspection after the replacement. This document proves to your insurance company that your new roof has the latest hurricane straps, secondary water barriers, and HVHZ-compliant fasteners.

    The Fix: A Wind Mitigation Inspection costs about $150, but in Miami, it can slash your annual homeowners' insurance premium by 30% to 50%. Tell your contractor you want the "Final Inspection" paperwork and a Wind Mitigation report as part of the closing package.

    Summary of 2026 Miami Roofing Costs

    Material Type Estimated Cost (2,000 sq. ft.) Expected Lifespan Benefit
    Architectural Shingles $12,000 – $19,000 18–25 Years Cost-effective, Popular
    Concrete Tile $22,000 – $38,000 30–50 Years Classic Miami Look
    Standing Seam Metal $25,000 – $45,000 40–70 Years Best Wind Resistance
    TPO (Flat Roofs) $8 – $15 per sq. ft. 15–20 Years Modern, Energy Efficient

    The Bottom Line

    Miami roofing is a specialized field. Between the heat, the salt air, and the hurricane risks, you cannot afford to cut corners. By avoiding these seven mistakes, you ensure your home stays protected and your investment holds its value.

    Ready to see what a code-compliant, hurricane-ready roof will cost for your specific address? Don't wait for the next storm.

    Get your free, instant satellite roof estimate for your Miami home here.

    Colonial-style Miami house with a reflective white metal roof

    Frequently Asked Questions (FAQ)

    How much does a new roof cost in Miami in 2026?
    For a standard 2,000 sq. ft. home, expect to pay between $10,000 and $28,000 for shingles. Tile and metal roofs typically range from $25,000 to $45,000+ depending on complexity and material quality.

    Do I really need a permit for a roof repair in Miami?
    Yes. In Miami-Dade County, any significant roofing work requires a permit to ensure it meets the High Velocity Hurricane Zone (HVHZ) building codes.

    What is the best roofing material for South Florida?
    Metal roofing and concrete tiles are highly recommended for their longevity and wind resistance. However, high-quality architectural shingles are the most popular choice for balancing cost and protection.

    How long does it take to get a roof estimate?
    Traditionally, it takes 3-5 days to schedule a contractor visit. With Get My Roof Estimate Now, you can get a satellite-powered estimate in under 60 seconds.

    Will a new roof lower my insurance in Miami?
    Yes, significantly. A new roof that meets 2026 HVHZ standards, specifically with a secondary water barrier and proper hurricane clips, can result in substantial "Wind Mitigation" discounts on your policy.
  • The Ultimate Guide to Nashville Roof Insurance: Everything You Need to Succeed

    The Ultimate Guide to Nashville Roof Insurance: Everything You Need to Succeed

    If you live in Nashville, you know the drill. One minute it’s a beautiful 75-degree afternoon in Germantown, and the next, a wall of gray clouds is dumping golf-ball-sized hail over Davidson County. For homeowners, that sound of ice hitting the roof isn't just loud, it's expensive.

    Navigating the world of roof insurance in Middle Tennessee can feel like trying to drive through the I-40/I-65 split during rush hour: confusing, high-stakes, and full of people trying to cut you off. But here’s the truth: your homeowners insurance is a product you pay for every month. When a storm hits, you aren't "getting lucky" if they pay for a new roof, you are simply receiving the benefit you’ve already bought.

    This masterclass will show you exactly how to handle the Nashville insurance claim process, from the first hailstone to the final shingle.

    1. The Nashville "Storm Reality" (April – September)

    Nashville sits in a unique "humid subtropical" zone that makes it a magnet for severe weather. Between April and September, the risk of severe thunderstorms and tornadoes spikes. These events bring two main enemies to your roof: Hail and High Winds.

    • Hail (The Impact): Even small hail can knock the protective granules off your shingles. Once those granules are gone, the underlying asphalt is exposed to the sun, leading to rapid deterioration and leaks.
    • Wind (The Lift): Nashville’s frequent wind gusts can "crease" shingles or lift them entirely, breaking the sealant bond that keeps your home watertight.

    Pro Tip: If you see "bruises" or dark spots on your shingles after a storm, that’s hail damage. If you see shingles that look like they’ve been folded back, that’s wind damage. Both are typically covered by standard Tennessee homeowners policies.

    A close-up photograph of asphalt shingles showing significant hail damage with circular indentations and granule loss.

    2. Deciphering Your Policy: RCV vs. ACV

    Before you file a claim, you need to know what kind of coverage you have. This is the single biggest factor in how much money stays in your pocket versus how much you have to pull from your savings.

    Replacement Cost Value (RCV) – [Premium/Popular]

    Most modern policies in Nashville are RCV. This means the insurance company pays to replace your roof with a brand-new one of "like kind and quality" at today’s prices.

    • How it works: They send an initial check (the depreciated value), and once the work is finished, they send a second check for the "recoverable depreciation."
    • Your cost: Typically just your deductible.

    Actual Cash Value (ACV) – [Budget]

    Some older or "budget" policies only cover the depreciated value of the roof.

    • How it works: If your 20-year-old roof is destroyed, they only pay what a 20-year-old roof is worth today.
    • Your cost: Your deductible PLUS the thousands of dollars in depreciation.

    The Nashville Rule: Check your "Declarations Page." If you see "ACV" listed under your roof coverage, be prepared for a higher out-of-pocket cost.

    3. The 5-Step Claim Masterclass

    Timing is everything. In Tennessee, most policies require you to file a claim within one year of the "Date of Loss" (the day the storm happened). Wait too long, and your claim will be denied automatically.

    Step 1: Document Everything

    Immediately after a storm, take photos of your yard (if there’s hail on the ground), your gutters (look for dents), and any leaks inside.

    Step 2: Get a Professional Baseline

    Don't call the insurance company first. Get an objective measurement of your roof's size and potential cost. Using a service like our instant roof estimate tool gives you a data-backed price range based on satellite imagery. This ensures that when the insurance adjuster gives you a number, you already know if it’s too low.

    Step 3: File the Claim

    Call your insurer’s claims department. Provide the date of the storm and a brief description of the damage. They will assign an "Adjuster" to visit your home.

    Step 4: The Adjuster Meeting

    Never let an adjuster walk your roof alone. Have a trusted local roofing contractor there to meet them. Your contractor will point out "hail hits" and "wind creases" that the adjuster might "miss."

    Step 5: Review the Scope of Work

    The insurance company will send you a "Statement of Loss." This is a line-by-line breakdown of what they are paying for. Ensure they included things like:

    • Ice and Water Shield (Required by Nashville building codes)
    • Drip Edge
    • Ventilation upgrades

    A Nashville homeowner using a tablet to view an instant satellite-powered roof estimate, showing a satisfied expression.

    4. Nashville Roofing Costs: What to Expect

    If you are paying out-of-pocket or dealing with a high deductible, here is what the Nashville market looks like in 2026. Prices in Davidson County are slightly higher than in rural Tennessee due to labor demand and permit requirements.

    Tier Material Estimated Cost (2,000 sq. ft. roof) Expected Lifespan
    Budget 3-Tab Shingles $7,500 – $9,500 15-20 Years
    Popular Architectural Shingles $11,500 – $14,500 25-30 Years
    Premium Standing Seam Metal $20,000 – $28,000 50+ Years

    Note: These estimates factor in the humid Nashville climate, which requires high-quality underlayment to prevent algae growth.

    5. Avoiding the "Storm Chaser" Trap

    After a big storm in neighborhoods like East Nashville or Sylvan Park, you’ll see trucks with out-of-state plates knocking on doors. These are "storm chasers." They do the work fast, take the insurance money, and disappear.

    The Checklist for a Real Nashville Pro:

    1. State License: Verify them with the Tennessee State Board for Licensing Contractors.
    2. Local Address: Do they have a physical office in Middle Tennessee?
    3. Insurance: Ask for a current Certificate of Liability and Workers’ Comp.
    4. No Pressure: If they pressure you to sign a "contingency agreement" before you’ve even seen an estimate, walk away.

    How "Get My Roof Estimate Now" Simplifies the Process

    We started Get My Roof Estimate Now because we were tired of the "waiting game." Traditionally, you’d have to call three contractors, wait for them to show up, and wait another week for a quote, all before you even talked to insurance.

    With our satellite technology, we can measure your Nashville roof with 95% accuracy and give you a full price breakdown in under 60 seconds.

    Why this matters for your insurance claim:

    • Transparency: You get an objective "Third-Party" cost estimate to compare against the insurance adjuster’s numbers.
    • Speed: You can decide if a claim is even worth filing (is the damage higher than your deductible?) in one minute.
    • No Pressure: We provide the data; you decide how to use it.

    A modern suburban home in Tennessee featuring a sleek, charcoal-colored standing seam metal roof and high curb appeal.

    Final Thoughts for Music City Homeowners

    Your roof is the most important structural element of your home. In a city where the weather changes as fast as the setlist at a Broadway honky-tonk, you can't afford to guess.

    Whether you’re in Franklin, Brentwood, or right in the heart of Nashville, being proactive after a storm is the key to a successful insurance claim. Use the technology available to you, vet your contractors, and don't take "no" for an answer if you know your roof is damaged.

    Ready to see what a new roof would cost for your Nashville home?
    Get your free, 60-second satellite roof estimate right here.


  • Charlotte Roof Replacement Cost Explained in Under 3 Minutes

    Charlotte Roof Replacement Cost Explained in Under 3 Minutes

    If you own a home in the Queen City, you know that our weather: from humid summer afternoons to sudden spring hailstorms: takes a heavy toll on your roof. When it’s time for a replacement, the first question is always: "How much is this going to cost me?"

    In Charlotte, NC, most homeowners spend between $6,000 and $22,000 for a full roof replacement. For a typical 2,000-square-foot roof using popular architectural shingles, the average price lands right around $9,000 to $14,000.

    At Get My Roof Estimate Now, we believe you shouldn't have to wait days for a contractor to show up just to get a ballpark figure. We use satellite imagery to provide instant roof estimates in under 60 seconds with 90-95% accuracy.


    The Charlotte Quick-Reference Cost Guide

    Roofing costs are calculated in "squares" (a 10×10 foot area, or 100 square feet). In the Charlotte market, prices are currently stable but reflect regional labor rates and material availability.

    1. Cost by Material Category

    Your choice of material is the single biggest factor in your final bill.

    Category Material Type Price Per Sq. Ft. (Installed) Total (2,000 Sq. Ft. Roof)
    Budget 3-Tab Asphalt Shingles $3.50 – $4.50 $7,000 – $9,000
    Popular Architectural Shingles $4.50 – $6.50 $9,000 – $13,000
    Premium Standing Seam Metal $10.00 – $16.00 $20,000 – $32,000
    Luxury Natural Slate or Tile $15.00 – $30.00+ $30,000 – $60,000+

    Close-up of high-quality architectural asphalt shingles

    2. Cost by Roof Size

    Not all homes are created equal. Use these ranges based on the actual surface area of your roof (which is often 20-30% larger than your home's interior square footage due to pitch and overhangs).

    • 1,500 Sq. Ft. Roof: $6,000 – $9,000 (Budget) | $12,000 – $18,000 (Premium)
    • 2,000 Sq. Ft. Roof: $8,000 – $12,000 (Budget) | $16,000 – $30,000 (Premium)
    • 2,500 Sq. Ft. Roof: $10,000 – $15,000 (Budget) | $20,000 – $40,000 (Premium)

    Why Charlotte Estimates Vary: The 4 "Hidden" Variables

    While square footage and material are the foundations of your estimate, four local factors can push your price toward the higher end of the range.

    1. Roof Pitch (The "Steepness" Factor)

    Charlotte’s historic neighborhoods, like Dilworth or Elizabeth, feature many homes with steep pitches. If your roof is too steep to walk on without safety harnesses, labor costs increase significantly. Steep roofs (8/12 pitch or higher) require more time and specialized equipment.

    2. Complexity and Waste

    A simple "up and over" ranch-style roof in Matthews will always cost less than a complex roof with multiple dormers, valleys, and chimneys in Ballantyne. More valleys mean more flashing and more material waste, which adds to the bottom line.

    3. Tear-Off Layers

    North Carolina building codes generally allow for two layers of shingles. However, most experts recommend a full tear-off to inspect the decking beneath. If your home currently has two layers of old shingles, expect to pay an additional $100 to $200 per square for the extra labor and disposal fees.

    4. Local Permits and Inspections

    Mecklenburg County requires permits for roof replacements. A reputable Charlotte contractor will handle the paperwork, but permit fees (usually based on the project value) will be factored into your total cost.

    Modern ranch-style home in Charlotte with a sleek black metal roof


    The Charlotte Climate Factor: Shingles vs. Metal

    Choosing a material isn't just about looks; it's about performance in the Piedmont region.

    • Architectural Shingles (The Gold Standard): These are the most common choice in Charlotte. They offer excellent wind resistance (up to 130 mph) and handle our high humidity well. Look for shingles with "Algae Resistance" to prevent those unsightly black streaks common in the South.
    • Metal Roofing (The Lifetime Investment): With Charlotte's intense summer sun, metal roofs reflect heat better than asphalt, potentially lowering your AC bills by 10-25%. They also stand up better to the hail that occasionally rolls through Mecklenburg County.

    Get a Precise Estimate in 60 Seconds: No House Call Needed

    The traditional way to get a roof estimate involves scheduling appointments, waiting for contractors to show up, and dealing with high-pressure sales pitches in your living room.

    Get My Roof Estimate Now changes that. We use advanced satellite imagery to measure your roof's exact dimensions, pitch, and complexity from above.

    1. Enter Your Address: We locate your home via satellite.
    2. Instant Measurement: Our tech calculates the "squares" with 90-95% accuracy.
    3. Transparent Pricing: You receive a detailed low-middle-high price range based on current Charlotte labor and material rates.

    No credit card is required, and you’ll have the data you need to budget for your project instantly.

    Satellite imagery measurement of a residential roof in Charlotte


    Charlotte Roofing FAQ: Quick Answers

    How much does a roof permit cost in Charlotte, NC?

    In Mecklenburg County, permit fees are typically tiered based on the total cost of the project. Most residential roof permits fall between $100 and $300. Your contractor should include this in their written quote.

    What is the best time of year to replace a roof in Charlotte?

    Spring (March-May) and Fall (September-November) are the peak seasons. The mild temperatures are ideal for shingle adhesion. While summer is possible, extreme heat can make shingles too soft to work on during midday.

    Does homeowners insurance cover roof replacement in Charlotte?

    If your roof was damaged by a specific event: like the hail storms common in the Piedmont or high winds from a tropical system: insurance may cover the cost minus your deductible. Normal wear and tear or "age-out" is generally not covered.

    How long does a typical roof replacement take?

    For most 1,500 to 2,500 sq. ft. homes in Charlotte, a professional crew can complete the tear-off and installation in 1 to 2 days, weather permitting.


    Ready to see your number?

    Don't guess what your new roof will cost. Get an accurate, satellite-powered estimate right now.

    Get Your Free Charlotte Roof Estimate Now


  • 7 Mistakes You’re Making with Houston Roofing Contractors (And How to Spot a Storm Chaser)

    7 Mistakes You’re Making with Houston Roofing Contractors (And How to Spot a Storm Chaser)

    In Houston, a roof isn’t just about curb appeal; it’s your primary defense against 95°F humidity, sudden tropical downpours, and the occasional hurricane. When your roof reaches the end of its 15- to 25-year lifespan, or a massive hailstorm rolls through Harris County, the pressure to find a contractor is intense.

    Unfortunately, this pressure often leads to costly errors. Whether you're in Sugar Land, Katy, or The Heights, the roofing market is flooded with both high-quality professionals and opportunistic "storm chasers."

    Here are the seven most common mistakes Houston homeowners make when hiring a roofing contractor and the technical data you need to avoid them.

    1. Falling for the "Free Roof" (Waived Deductible) Scam

    This is the most common: and dangerous: mistake in Texas. A contractor may offer to "cover" or "waive" your insurance deductible to win the job.

    The Reality: In Texas, this is illegal. Under Texas Law (HB 2102), it is a criminal offense for a roofing contractor to pay, waive, or rebate a policyholder’s deductible. If a contractor offers this, they are asking you to participate in insurance fraud. Furthermore, any contractor willing to break state law to get your business is likely to cut corners on your installation to recoup that "waived" cost.

    2. Hiring Out-of-State "Storm Chasers"

    After a significant weather event, "storm chasers" flood the Houston area. These are companies that travel from state to state following storm paths.

    How to Spot Them:

    • Out-of-state plates: Check the trucks. If they aren’t from Texas, proceed with extreme caution.
    • Door-to-door solicitation: Reputable local contractors are usually busy enough with referrals; they rarely need to knock on doors.
    • No local address: If their business card lists a P.O. Box or a temporary office space, they will likely be gone long before your warranty issues arise.

    Close-up photograph of high-quality architectural asphalt shingles on a residential roof.

    3. Signing a "Contingency Agreement" Before an Estimate

    A common tactic involves a contractor asking you to sign a "simple form" that allows them to talk to your insurance company.

    The Risk: Many of these forms are legally binding contingency agreements. By signing, you may be committing to use that contractor for the full amount of the insurance settlement before you’ve even seen a formal price quote. Always get an instant roof estimate first so you know the baseline cost (Budget, Popular, or Premium) before engaging with insurance paperwork.

    4. Paying 100% of the Cost Upfront

    No reputable Houston roofing company requires full payment before they drop materials in your driveway.

    Standard Practice:

    • Deposit: Typically 1/3 or 1/2 of the total project cost to cover materials.
    • Final Payment: Due only after the job is complete, the site is cleaned (magnetic sweep for nails), and you’ve signed off on the work.
    • Red Flag: If a contractor demands the full check upfront because they "need to buy materials," it’s a sign of financial instability or a potential disappearance.

    5. Ignoring Houston-Specific Material Requirements

    Houston’s climate is brutal. A mistake many make is choosing the cheapest material without considering the "Texas Tax": the cost of premature failure due to heat.

    Factor Impact on Houston Roofs Recommended Solution
    Humidity Promotes algae and mold growth. Algae-resistant shingles (copper-lined granules).
    UV Exposure Rapidly degrades standard asphalt binders. Reflective "Cool Roof" shingles or Metal.
    Wind High risk during Hurricane season. Shingles with 130 mph+ wind ratings.

    For many Houstonians, Metal Roofing is becoming the "Premium" standard because it reflects solar heat, potentially lowering cooling bills by 10-25%.

    Modern Texas home with a sleek charcoal grey standing seam metal roof.

    6. Not Verifying Insurance and Local Registration

    Texas does not have a statewide roofing license, which makes vetting even more critical.

    Must-Haves:

    • General Liability Insurance: Protects your property if a tree branch falls or a leak occurs during construction.
    • Workers’ Compensation: Ensures you aren't liable if a crew member is injured on your property.
    • City Registration: Most municipalities (like the City of Houston or Pearland) require contractors to register and pull permits. If they skip the permit, they are skipping the city inspection that protects you.

    7. Relying on "Eyeball" Estimates

    Many traditional contractors walk the perimeter of your house and give you a "ballpark" figure. This leads to "change orders" halfway through the job when they realize the roof is steeper or larger than they thought.

    The Solution: Use technology. Our satellite-powered measurement system provides 90-95% accuracy without anyone stepping on your shingles. In 60 seconds, you can receive a data-driven range for your specific address:

    • Budget ($8,500 – $11,000): 3-tab shingles for standard homes.
    • Most Popular ($12,000 – $16,000): Architectural shingles with high wind resistance.
    • Premium ($20,000 – $35,000+): Standing seam metal or designer tiles.

    Homeowner in Houston holding a modern smartphone showing a satellite imagery map of their roof with a clear price estimate.

    Conclusion: Take Control of the Process

    Replacing a roof is one of the most significant investments you'll make in your Houston home. Don't let high-pressure sales tactics or storm-chaser gimmicks cloud your judgment.

    By starting with a transparent, satellite-accurate estimate, you ground the conversation in reality. You’ll know exactly how many "squares" your roof is and what the market rate is for materials and labor in your specific zip code.

    Don't wait for a leak. Get your free Houston roof estimate in 60 seconds today.


  • The Ultimate Guide to Atlanta Roof Replacement Cost: Everything You Need to Succeed in 2026

    The Ultimate Guide to Atlanta Roof Replacement Cost: Everything You Need to Succeed in 2026

    For Atlanta homeowners, 2026 marks a turning point in home maintenance. As we move further into the decade, the combination of regional labor shortages and a projected 4–8% hike in material costs has changed the math on roof replacements. If you are sitting under a 20-year-old roof in Buckhead, Marietta, or Decatur, waiting another year could cost you thousands in inflation alone.

    In Atlanta, a roof isn't just about curb appeal: it’s a critical defense against humid subtropical heat, heavy spring downpours, and the occasional North Georgia hail storm. This guide breaks down the cold, hard numbers for 2026 to help you plan with 95% accuracy.

    The 2026 Atlanta Cost Snapshot

    In 2026, the average cost for a full roof replacement in the Atlanta metro area ranges from $8,500 to $22,000. For premium materials or oversized estates, these figures can easily climb toward $30,000+.

    Component Estimated Cost (2026) Notes
    Basic 3-Tab Shingle $3.75 – $5.25 / sq. ft. (Budget) Best for short-term fixes.
    Architectural Shingle $4.75 – $6.75 / sq. ft. (Popular) The gold standard for GA homes.
    Standing Seam Metal $11.00 – $15.50 / sq. ft. (Premium) High ROI and energy efficiency.
    Labor Share 45% – 60% of total Higher in metro Atlanta than rural GA.
    Permits & Disposal $1,200 – $3,500 Includes Fulton/DeKalb fees and debris.

    Decoding the Materials: What’s Best for Your Zip Code?

    Choosing the right material is a balance of upfront cost and long-term durability. In the Atlanta market, three categories dominate the landscape:

    1. Asphalt Shingles (The Standard Choice)

    Asphalt remains the most common choice due to its versatility and lower price point.

    • 3-Tab Shingles (Budget): These are the most affordable option. While they meet building codes, they are thinner and more susceptible to wind damage during Atlanta’s storm season (March–August).
    • Architectural Shingles (Popular): Also known as dimensional shingles, these are the preferred choice for 80% of our Atlanta clients. They offer superior wind resistance (up to 130 mph) and a layered look that mimics wood shakes.

    Hyper-realistic close-up photography showing a comparison between basic 3-tab asphalt shingles on the left and thick, textured architectural shingles on the right.

    2. Metal Roofing (The Performance Choice)

    Metal Roofing (Premium): With Atlanta’s summer highs frequently hitting 90°F+, metal roofs are gaining massive popularity. A standing seam metal roof reflects solar radiant heat, which can reduce cooling costs by up to 25%. While the initial investment is 2-3x higher than shingles, a metal roof in Georgia can last 50+ years, often outlasting the homeowner's tenure.

    A hyper-realistic photograph of a modern Atlanta home with a sleek, dark bronze standing seam metal roof. The architecture is contemporary with large windows and brick accents.

    The "Atlanta Factor": Local Variables That Influence Price

    Your neighbor’s roof quote might be $12,000, while yours is $18,000. Why? Several local factors dictate the final invoice:

    • Roof Complexity: Atlanta’s historic homes in neighborhoods like Inman Park or Grant Park often feature steep pitches (8/12 or higher) and multiple dormers. Steep roofs require specialized safety equipment and more man-hours, increasing labor costs by 20–40%.
    • Tree Canopy: Atlanta is famously the "City in a Forest." While beautiful, heavy tree cover leads to more organic debris and potential rot. If a contractor discovers rotted decking (the wood layer under the shingles) during the tear-off, expect to pay $75–$110 per sheet of plywood replaced.
    • Permitting and Waste: Fulton and DeKalb counties have specific requirements for debris disposal. A reputable contractor will include the cost of a dumpster and local permits: usually between $175 and $500: directly in your roof cost estimate.

    Why "Ballpark" Estimates Are a Risk in 2026

    In the past, homeowners had to wait days for a contractor to show up with a ladder and a tape measure. These "eyeball" estimates were often inaccurate, leading to "change orders" that inflated the price mid-project.

    In 2026, technology has eliminated this friction. At Get My Roof Estimate Now, we use high-resolution satellite imagery to measure your roof with precision down to the inch. We analyze the exact square footage, pitch, and number of valleys without ever stepping foot on your property.

    A high-tech visualization of a residential roof in Atlanta being measured by satellite imagery, showing glowing blue digital wireframe lines and measurement labels.

    The 60-Second Advantage

    By using our roof cost calculator, you get:

    1. Instant Transparency: No high-pressure sales meetings in your living room.
    2. Accurate Data: Measurements that are 90-95% accurate to the actual build.
    3. Vetted Connections: We connect you with licensed, insured Atlanta contractors who are ready to honor the satellite-generated pricing.

    Budgeting for Success: Your 2026 Checklist

    If you are planning a replacement this year, follow these three steps to ensure you don't overpay:

    1. Get Your Baseline: Use a free roof estimate tool to establish a "fair market" price based on your specific roof geometry.
    2. Time Your Project: If possible, schedule your replacement for late winter (January–February). Demand is lower, and some Atlanta contractors offer 5–10% off-season discounts to keep their crews busy.
    3. Check the Warranty: Ensure your quote includes both a Manufacturer Warranty (covering the shingles) and a Workmanship Warranty (covering the installation). In 2026, a 10-year workmanship warranty is the industry standard for quality GA pros.

    Conclusion

    Replacing a roof in Atlanta is a significant investment, but it shouldn't be a mystery. By understanding the 2026 material hikes and leveraging satellite technology, you can move forward with confidence. Whether you’re looking for a budget-friendly 3-tab shingle or a premium metal system to combat the Georgia heat, the data is now at your fingertips.

    Ready to see your number? Get your instant Atlanta roof estimate in 60 seconds. No credit card, no hassle, just accurate pricing.

    Get Your Free Estimate Now


  • The Ultimate Guide to Vetting Lafayette Contractors: Everything You Need to Spot a Scam

    Lafayette homeowners are no strangers to the volatile weather of the Gulf Coast. From the seasonal threat of hurricanes to the sudden, heavy thunderstorms that roll through Acadiana, your roof is your first line of defense. Unfortunately, where there is storm damage, there are "storm chasers": unscrupulous contractors who descend on neighborhoods like Broadmoor or River Ranch after a weather event, looking to exploit stressed homeowners.

    Vetting a contractor in Lafayette isn't just about finding someone who can swing a hammer; it’s about navigating complex Louisiana state laws and spotting sophisticated scams before you sign a contract. This guide provides the data-driven framework you need to protect your home and your wallet.

    The New Reality of Louisiana Roofing Laws

    As of 2025 and 2026, Louisiana has significantly tightened the screws on the roofing industry. If you haven't hired a roofer in a few years, the rules have changed. Understanding these legal benchmarks is your first step in vetting.

    The $7,500 Threshold (Licensing)

    In Louisiana, any residential roofing project valued at $7,500 or more requires the contractor to hold a specific license from the Louisiana State Licensing Board for Contractors (LSLBC).

    • Residential Roofing License (New): Effective January 2026, contractors must pass a specific trade exam for residential roofing.
    • Exemptions: Contractors holding a "Residential Construction" or "Building Construction" license are also authorized to perform this work.

    The Scam: A contractor claims they don't need a license because they are "just doing a repair," even if the quote is $10,000. If they aren't in the LSLBC database, they are operating illegally.

    Mandatory Permits and Inspections

    Under Act 239, all roof construction and reroofing projects in Louisiana: regardless of the price: now require a permit and inspections.

    • The Red Flag: If a contractor tells you a permit isn’t necessary for a simple reroof in Lafayette, they are lying.
    • The Risk: Without a permit and a subsequent inspection, you have no proof the roof meets the Louisiana State Uniform Construction Code. This can haunt you during a future home sale or insurance claim.

    4 Red Flags: How to Spot a "Storm Chaser" in Lafayette

    Storm chasers are high-pressure sales outfits that follow hail and wind maps. They aren't local, and they often disappear once the check clears. Look for these four specific warning signs.

    1. The "Free Roof" or Deductible Scam

    This is the most common scam in the South. A contractor offers to "waive," "eat," or "rebate" your insurance deductible.

    • The Reality: This is insurance fraud. Your deductible is a legal obligation between you and your insurer.
    • The Tactic: The contractor often inflates the invoice sent to the insurance company to cover the cost of your deductible. If the insurance company finds out, you could be held liable for fraud.

    2. The Door-to-Door Pressure Play

    Reliable Lafayette roofing companies are usually busy enough that they don't need to knock on doors randomly.

    • The Red Flag: A salesman who claims they "just finished a roof down the street" and noticed "obvious damage" from the ground. They will push for an immediate "free inspection" to get you to sign a contingency agreement.
    • The Vetting Rule: Never sign a document just to get an inspection. A contingency agreement often locks you into using that contractor if your insurance claim is approved.

    A hyper-realistic aerial satellite view of a residential neighborhood in Lafayette, LA, highlighting various roof shapes and sizes, representing advanced roofing measurement technology.

    3. Out-of-State Plates and Non-Local Numbers

    Check the trucks and the business cards. Storm chasers often use temporary magnetic signs on their vehicles.

    • Lafayette Context: Look for a 337 area code and a physical office address in the Lafayette/Acadiana area. A PO Box or a hotel address is a major warning sign.
    • Why it Matters: If your roof leaks six months from now, a contractor based in Texas or Florida won't come back to fix it under warranty.

    4. Large Upfront Deposits

    While a small deposit for materials is standard (typically 10-33%), a contractor asking for 50% or more upfront before a single shingle arrives is a flight risk.

    • The Scam: They take your insurance "first check" (the ACV payment) and simply never return to start the work.

    The Step-by-Step Vetting Checklist

    Before you hand over a dime, run every Lafayette contractor through this rigorous checklist.

    Step Action Why it Matters
    1. LSLBC Search Search the LSLBC database by name. Confirms they are legally allowed to work in LA.
    2. Insurance Verification Demand a Certificate of Insurance (COI) sent directly from their agent. Protects you if a worker falls or your property is damaged.
    3. Permit Confirmation Ask who will pull the permit (it should be them). Ensures the work is inspected by Lafayette Parish/City officials.
    4. Local References Ask for three Lafayette addresses they roofed in the last 12 months. Verifies they have a history in the community.
    5. Material Specs Ensure the contract lists specific brands (e.g., GAF, Owens Corning). Prevents "bait and switch" with lower-quality materials.

    Utilizing Technology to Level the Playing Field

    The biggest advantage a scammer has is information asymmetry. They know how much a roof costs; you don't. They claim your roof is 30 "squares" (3,000 sq. ft.); you have no way to verify that without climbing a ladder.

    At Get My Roof Estimate Now, we use satellite imagery technology to provide Lafayette homeowners with an objective, third-party benchmark. By entering your address into our Roof Cost Calculator, you receive an estimate accurate to within 90-95% of the actual size and cost: all in under 60 seconds.

    How this stops scams:

    • Accurate Sizing: If our satellite measurement shows your roof is 22 squares and a contractor quotes you for 30, you know they are padding the bid.
    • Price Transparency: We provide low-middle-high ranges based on current Lafayette material and labor costs. If a "storm chaser" quotes you $25,000 for a project our data shows should cost $14,000, you have the evidence to walk away.

    A professional roofing crew wearing safety harnesses working on a steep residential roof in a sunny, tree-lined neighborhood, hyper-realistic photography.

    Understanding Lafayette Roofing Costs (2026 Benchmarks)

    To vet a quote effectively, you need to know the baseline. For a typical 2,000-square-foot home in Lafayette, here is what you should expect to pay for a full replacement:

    • Architectural Shingles (Popular): $9,500 – $14,000. These are the standard for most Lafayette neighborhoods due to their wind resistance (up to 130 mph).
    • Metal Roofing (Premium): $18,000 – $32,000. Standing seam metal is increasingly popular in South Louisiana for its longevity and hurricane durability.
    • Synthetic/Slate (Luxury): $35,000+. Often seen in high-end developments or historic districts.

    Note: These prices factor in regional labor rates and current Louisiana disposal fees.

    Final Thoughts: Trust, But Verify

    Lafayette is a community built on handshakes and local trust, but the roofing industry attracts outsiders who don't share those values. Protecting your home starts with a refusal to be rushed.

    If a contractor is pressuring you, walk away. If they won't provide a license number, walk away. And if you want to know exactly what your roof should cost before you ever speak to a salesman, start with an instant satellite estimate.

    Knowledge is your best defense against a scam. Take 60 seconds to get the data you need to vet your Lafayette contractor like a pro.

    Close-up detail of high-quality architectural roofing shingles in a charcoal grey color, showing texture and depth, hyper-realistic photography.

  • 2026 Mobile Roof Pricing Explained in Under 3 Minutes

    2026 Mobile Roof Pricing Explained in Under 3 Minutes

    For homeowners in Mobile, Alabama, the question of roof replacement cost is often urgent. Between the high humidity of the Gulf Coast and the looming threat of hurricane season, your roof is more than just an aesthetic choice, it’s your primary line of defense.

    In 2026, a standard roof replacement in Mobile typically ranges from $6,000 to $28,000, with most homeowners landing in the $10,500 to $16,000 bracket. This guide breaks down the data, material costs, and local variables specific to the Port City so you can budget accurately without the guesswork.

    The 2026 Mobile Pricing Snapshot

    If you are looking for a quick baseline, the average cost per square foot in Alabama currently sits between $3.20 and $7.50 for asphalt systems. However, your total investment depends heavily on material choice and the complexity of your roofline.

    Material Type Cost Per Sq. Ft. (Installed) Avg. Total (2,000 Sq. Ft. Roof)
    3-Tab Asphalt (Budget) $3.00 – $4.50 $6,000 – $9,000
    Architectural Shingles (Popular) $4.50 – $7.50 $9,000 – $15,000
    Metal Roofing (Premium) $9.00 – $14.00 $18,000 – $28,000
    Tile or Synthetic (High-End) $10.00 – $20.00 $20,000 – $40,000+

    Why Your Mobile Location Matters

    Mobile is unique. Unlike landlocked cities in Alabama, roofs here face extreme salt spray, high-velocity winds, and intense UV exposure. In 2026, roofing technology has advanced to meet these needs, but it impacts the "bottom line" in three specific ways:

    1. Wind Mitigation Standards: Mobile falls within designated wind zones. Local building codes often require specific nailing patterns or high-wind-rated shingles (up to 130 mph), which can slightly increase labor and material costs compared to inland cities like Birmingham.
    2. Humidity and Algae: "Gloeocapsa magma", the blue-green algae that causes black streaks, thrives in our humid climate. Most 2026 estimates now include algae-resistant shingles as a standard, not an upgrade.
    3. Insurance Requirements: Many Alabama homeowners are now prioritizing FORTIFIED Home™ standards to lower their insurance premiums. While this can add 5-10% to your upfront cost, the long-term savings and peace of mind during storm season are significant.

    Satellite imagery measurement of a residential roof in Mobile Alabama

    How We Calculate Your Estimate in 60 Seconds

    The traditional way of getting a roof estimate, scheduling three contractors to climb on your house, is becoming a thing of the past. At Get My Roof Estimate Now, we use advanced satellite imagery to measure your roof with 95% accuracy.

    By entering your address into our Roof Cost Calculator, our system analyzes:

    • Total Square Footage: Measured in "squares" (100 sq. ft. sections).
    • Roof Pitch: Steeper roofs require more safety equipment and labor.
    • Complexity: The number of valleys, dormers, and chimneys.
    • Regional Labor Rates: Real-time data from Mobile-area contractors.

    This technology allows you to skip the sales pitch and move directly to the budgeting phase.

    Deep Dive: Material Costs for 2026

    1. Architectural Shingles (The Standard Choice)

    In 2026, architectural (or dimensional) shingles remain the top choice for Mobile homeowners. They offer a balance of durability and cost-effectiveness.

    • Budget Range: $9,000 – $15,000 for a typical home.
    • Why: They provide a multi-layered look and better wind resistance than 3-tab shingles.
    • Mobile Factor: Look for "Cool Roof" shingles that reflect sunlight to keep your AC bills lower during the sweltering July heat.

    2. Metal Roofing (The Performance Choice)

    Metal is rapidly gaining market share in Alabama due to its longevity.

    • Budget Range: $18,000 – $28,000.
    • Why: A well-installed standing seam metal roof can last 50+ years.
    • Mobile Factor: Metal is highly resistant to wind uplift, making it a favorite for homes near Mobile Bay or the Dog River.

    Close-up of a silver-gray standing seam metal roof installation

    3. Designer and Synthetic Shingles (The Luxury Choice)

    For historic homes in the De Tonti Square or Oakleigh districts, synthetic slate or cedar shakes offer a high-end look without the weight and maintenance of natural materials.

    • Budget Range: $20,000+.
    • Why: Unmatched curb appeal and premium warranty protection.

    The Components of a Professional Estimate

    When you receive a quote through our platform, it isn't just a single number. We break it down into the core logistical factors that drive the price:

    • Tear-Off and Disposal: Removing your old roof usually costs around $100 to $150 per square. If you have multiple layers of old shingles, this price can increase.
    • Underlayment: In Mobile, we recommend synthetic underlayment over traditional felt. It creates a secondary water barrier that is crucial when those afternoon thunderstorms hit.
    • Flashing and Ventilation: Replacing rusted flashing around chimneys and ensuring proper attic ventilation (ridge vents or solar fans) accounts for roughly 10-15% of the total project cost.
    • Permits: In Mobile County, permit fees vary but are a necessary line item for any licensed and insured contractor.

    Professional roofing crew installing shingles on a suburban Mobile home

    How to Save Money on Your 2026 Replacement

    While a new roof is a major investment, there are ways to manage the cost without cutting corners on quality:

    1. Off-Season Scheduling: While roofing happens year-round in Alabama, scheduling your replacement in the "shoulder seasons" (late fall or early spring) can sometimes lead to lower labor rates as demand dips slightly.
    2. Insurance Claims: If your roof was damaged in a recent storm, your homeowner's insurance may cover a significant portion of the cost. Always have a professional assessment done before filing.
    3. Use Technology: By using our instant estimate tool, you can compare different material costs immediately. Seeing the price difference between architectural shingles and metal in real-time helps you make an informed decision without pressure.

    Ready for Your Mobile Roof Estimate?

    Transparency is our priority. We believe every homeowner in Mobile deserves to know exactly what they are paying for before they invite a contractor to their doorstep.

    Whether you’re in Saraland, West Mobile, or downtown, you can get an accurate, satellite-powered estimate right now. No credit card, no waiting, and no hassle.

    Click here to get your 60-second roof estimate for Mobile, AL.


  • The Ultimate Guide to Getting Insurance to Pay for Your New Roof in Mobile, AL

    Living in Mobile, AL, means enjoying the beauty of the Gulf Coast, but it also means dealing with some of the most volatile weather in the United States. Between hurricane season and severe afternoon thunderstorms, your roof takes a beating that homeowners in the Midwest simply don't experience.

    When storm damage strikes, the difference between a $15,000 out-of-pocket expense and a fully covered insurance replacement often comes down to how you handle the first 48 hours. This guide is a masterclass in navigating the Alabama insurance landscape to ensure you receive the full value of your policy.
    The High Stakes of Gulf Coast Homeownership

    In Mobile, a roof isn't just a cosmetic feature; it’s a structural shield. The high humidity, salt air, and extreme wind speeds (often exceeding 100 MPH during tropical events) mean that even minor shingle damage can quickly escalate into structural rot.

    According to current 2026 cost data, a full roof replacement for a standard 2,000-square-foot home in the Southeast averages between $9,000 and $22,000. If you aren't prepared to navigate a claim, you could be left footing that bill alone.

    Step 1: Identifying "Covered Perils" (Wind vs. Wear)

    Insurance companies do not pay for "old age." They pay for "sudden and accidental" damage caused by specific events, known as covered perils.

    • Wind Damage (Covered): In Alabama, this includes shingles that have been lifted, creased, or torn away by high winds.
    • Hail Damage (Covered): Direct impacts that bruise the shingle matting or cause significant granule loss.
    • Wear and Tear (Excluded): Curling, balding, or organic growth (moss) that occurs over 20 years of neglect.

    The Alabama 25% Rule: In many cases, if more than 25% of your roof is damaged by a covered storm event, Alabama insurance guidelines often lean toward a full replacement rather than a patch. This is because "matching" materials of like kind and quality is required to maintain the home’s value and structural integrity.

    Detailed photography of a residential roof in Alabama showing storm-damaged architectural shingles with creased tabs and missing sections after a severe wind storm, hyper-realistic.

    Step 2: The Critical Difference Between ACV and RCV

    Before you file a claim, you must check your "Declarations Page" for these two acronyms. They determine exactly how much cash you will actually see in your bank account.

    1. Replacement Cost Value (RCV – Premium): The insurance company pays for the current cost of a new roof. They may hold back "depreciation" until the work is finished, but they eventually cover the full bill (minus your deductible).
    2. Actual Cash Value (ACV – Budget): The insurer only pays what your roof is worth today. If your 20-year-old roof is destroyed, they will subtract 20 years of "use" from the payout. In Mobile, many older policies are being converted to ACV to save the insurer money: don't let this catch you by surprise.

    Step 3: Mitigation – The Homeowner’s Legal Duty in Alabama

    Alabama insurance law requires homeowners to take "reasonable steps" to prevent further damage after a storm. This is called mitigation.

    • Tarping: If you have a hole or missing shingles, you must have it tarped immediately.
    • Documentation: Take photos before the tarp goes on.
    • Reimbursement: Save the receipts from the emergency repair. Most carriers will reimburse these costs as part of the claim. Failure to mitigate can actually result in a claim denial for any subsequent water damage that occurs inside the home.

    Step 4: The 60-Second Benchmark – Using Satellite Data to Secure Your Claim

    The biggest conflict in any insurance claim is the "Scope of Work." The insurance adjuster might say your roof is 22 squares (2,200 sq. ft.), while a contractor says it’s 25 squares. Who is right?

    In the past, you had to wait for a contractor to climb your roof with a tape measure. Today, savvy Mobile homeowners use GetMyRoofEstimateNow.com to get a satellite-powered measurement report before the adjuster even arrives.

    Our technology uses high-resolution imagery to calculate:

    • Exact Square Footage (95%+ accuracy)
    • Roof Pitch and Complexity
    • Current Local Material Pricing (2026 updates)

    Having an objective, tech-backed estimate (typically generated in under 60 seconds) gives you the data needed to challenge an adjuster’s "lowball" measurements.

    High-resolution satellite view of a residential neighborhood in Mobile, AL, with a graphic overlay showing precise roof measurements, pitch calculations, and area highlights for a claim.

    Step 5: Navigating the Adjuster Meeting

    When the insurance adjuster visits your home, they are looking for reasons to minimize the payout. Here is how to handle the meeting professionally:

    • Be Present: Don't just leave a key. Be there to point out interior leaks or specific areas of concern.
    • The "No-Negotiation" Rule: Under Alabama law, a roofing contractor cannot legally negotiate your claim or act as your public adjuster. They can, however, provide a technical estimate and explain the damage to the adjuster.
    • Highlight Code Requirements: Mobile has specific building codes regarding "drip edges" and "ice and water shields" (though rarely needed for ice here, they are vital for wind-driven rain). Ensure the adjuster includes "Ordinance and Law" coverage if your policy provides it.

    The Local Advantage: Why Mobile Roofs Cost More

    Expect to pay a premium for labor and materials that meet the High-Velocity Hurricane Zone (HVHZ) standards often required in coastal Alabama.

    Material Type Estimated Cost (per sq. ft.) Expected Lifespan
    Architectural Shingles (Popular) $4.50 – $6.50 25 – 30 Years
    Standing Seam Metal (Premium) $10.00 – $14.00 50 – 70 Years
    Synthetic/Slate (Designer) $8.00 – $16.00 50+ Years

    Data based on 2026 regional averages for the Gulf Coast.

    If your insurance claim is approved, consider upgrading to a metal roof. While the insurer may only pay for the "like kind" shingle replacement, you can often pay the difference to upgrade to a system that offers better wind resistance and lower insurance premiums in the future.

    A modern Gulf Coast home in Mobile, Alabama, featuring a high-quality standing seam metal roof designed for maximum wind resistance, with palm trees and a clear blue sky.

    Summary: Your 60-Second Action Plan

    1. Verify Coverage: Confirm you have an RCV policy.
    2. Mitigate: Tarp the roof to prevent interior damage.
    3. Get Data: Use our Instant Roof Cost Calculator to get a satellite measurement of your home.
    4. File Promptly: Most Alabama policies require notice within 30-60 days of the storm.
    5. Connect with Pros: Use your Get My Roof Estimate report to interview verified local contractors who specialize in insurance claims.

    Don't let the insurance company dictate the value of your home’s most important asset. Start with accurate data and a professional plan.


  • Charlotte Roof Replacement Cost Explained in Under 3 Minutes

    Charlotte Roof Replacement Cost Explained in Under 3 Minutes

    If you are a homeowner in the Queen City, you already know that the Charlotte weather: ranging from humid subtropical summers to the occasional ice storm: puts a massive strain on your roof. When it comes time for a replacement, you don’t want to wait days for a contractor to "swing by" just to get a ballpark figure. You need data now.

    In 2026, the average roof replacement in Charlotte, NC typically costs between $8,500 and $16,000. For a standard 2,000-square-foot roof using mid-range materials, most Charlotte homeowners land right around the $11,500 mark.

    At Get My Roof Estimate Now, we leverage advanced satellite imagery to calculate your roof’s size, pitch, and complexity with 90-95% accuracy. This allows us to provide an instant, transparent price range in under 60 seconds without a single home visit.

    Quick Cost Breakdown by Material Tiers

    To help you categorize your choices, we’ve broken down Charlotte roofing costs into three primary tiers based on local 2026 market data.

    • Budget Tier ($6,000 – $8,500): Standard 3-tab asphalt shingles. Best for homeowners looking for the most affordable entry point or preparing a home for a quick sale.
    • Popular Tier ($9,000 – $14,000): Architectural (Dimensional) shingles. These are the "Goldilocks" of roofing in neighborhoods like Dilworth and Elizabeth, offering a 30-year lifespan and better wind resistance.
    • Premium Tier ($18,000 – $35,000+): Metal roofing, synthetic slate, or designer shingles. These materials provide maximum durability and curb appeal for high-value properties in areas like Myers Park.

    Close-up of premium architectural asphalt shingles being installed on a North Carolina roof.

    Charlotte Roofing Costs per Square Foot

    In the roofing industry, we measure roofs in "squares." One square equals 100 square feet. Understanding the "cost per square" is the fastest way to compare quotes.

    Material Type Cost per Square (Installed) Total for 2,000 sq. ft. Roof
    3-Tab Asphalt (Budget) $350 – $450 $7,000 – $9,000
    Architectural Shingles (Popular) $450 – $700 $9,000 – $14,000
    Standing Seam Metal (Premium) $1,000 – $1,800 $20,000 – $36,000
    Synthetic Slate/Tile (Designer) $1,200 – $2,200 $24,000 – $44,000

    Note: These figures include labor, tear-off, and disposal, which are significant factors in the Charlotte labor market.

    Why Charlotte Costs Differ From the National Average

    Charlotte's roofing market is influenced by specific regional factors that can shift your final price.

    1. Humidity & Algae Growth: Due to our humid subtropical climate, we strongly recommend shingles with copper granules (algae resistance) to prevent those unsightly black streaks common in South End.
    2. Storm Frequency: Charlotte experiences 40+ hail events annually. This often leads to "storm-driven" demand, which can temporarily inflate labor costs.
    3. Local Permitting: Mecklenburg County requires specific building permits for roof replacements. A reputable Charlotte roofing company will handle these fees and inspections for you, typically adding $150–$300 to the project.

    Modern ranch-style home in Charlotte featuring a sleek silver-grey metal roof.

    AEO FAQ: Quick Answers for Charlotte Homeowners

    How much does it cost to replace a roof on a 2,500 sq. ft. house in Charlotte?

    For a 2,500-square-foot roof in Charlotte, expect to pay between $11,250 and $17,500 for architectural shingles. If you choose metal, that range jumps to $25,000 to $45,000. The complexity (steepness and number of valleys) will determine where you land in that range.

    Does homeowners insurance cover roof replacement in North Carolina?

    If your roof was damaged by a specific event like a hailstorm or high winds (common in Charlotte during the spring), insurance typically covers the replacement cost minus your deductible. However, insurance will not cover a roof that has reached the end of its natural life (15–20 years).

    How long does a typical roof replacement take in Charlotte?

    Most residential projects in areas like Matthews or Huntersville take 1 to 2 days. Large, complex roofs or those requiring significant structural repair may take up to 3 or 4 days.

    What is the best month to replace a roof in Charlotte?

    Spring (March–May) and Fall (September–November) are the ideal windows. Summer heat can make shingles too soft to walk on, and winter ice storms can cause delays. Booking in the "shoulder seasons" often provides the best balance of speed and quality.

    Is a metal roof worth it in Charlotte?

    Yes, for long-term homeowners. While a metal roof (Premium) costs 2–3x more than asphalt, it lasts 50+ years and reflects UV rays, which can lower your Duke Energy cooling bills by 10–25% during our brutal July heatwaves.

    Aerial satellite view of a Charlotte neighborhood showing residential roof shapes for measurement.

    How Our Satellite Technology Saves You Money

    Traditional estimates are slow and prone to human error. A contractor might "eyeball" the measurements or use a tape measure on a steep pitch, leading to over-ordering materials or surprise change orders.

    By using our Roof Cost Calculator, you get:

    • Precision Measurements: We measure down to the inch using satellite data.
    • No Pressure: Get your price without a salesperson sitting at your kitchen table for two hours.
    • Verified Contractors: We connect you with licensed, insured pros who honor our data-driven pricing.

    Final Benchmark: The "Queen City" 2026 Pricing Summary

    If you are budgeting for a project this year, use these benchmarks for a standard 20-square (2,000 sq. ft.) roof:

    • Materials (Architectural Shingles): $4,000 – $5,500
    • Labor (Charlotte Average): $4,500 – $6,500
    • Waste/Disposal/Permits: $1,000 – $2,000
    • Total Estimated Investment: $9,500 – $14,000

    Don't guess on the single most important protection for your home. Use our Free Roof Estimate tool now to get your specific Charlotte address measured and priced in under a minute.

  • The Ultimate Guide to Vetting Miami Contractors: Everything You Need to Spot a Storm Chaser

    Miami is one of the most demanding roofing markets in the world. Between the punishing UV rays, salt air corrosion, and the ever-present threat of Atlantic hurricanes, your roof isn't just a covering: it’s a specialized structural shield. Because of this, Miami-Dade County maintains some of the strictest building codes in the United States.

    Unfortunately, where there is high demand and high insurance payouts, "storm chasers" follow. These are out-of-state contractors who descend on South Florida after a major weather event, sign dozens of contracts, perform subpar work, and vanish before the first leak appears.

    In this guide, we’ll show you exactly how to vet Miami contractors like a pro, identify the red flags of a storm chaser, and use modern technology to ensure you’re paying a fair market price.

    The Anatomy of a Storm Chaser: 5 Red Flags

    Storm chasers are masters of high-pressure sales. They often appear at your door within 48 hours of a wind or hail event. Here is what to look for:

    1. Out-of-State Plates and Phone Numbers

    If a contractor's truck has Georgia or Texas plates and their business card features a non-305 or 786 area code, proceed with extreme caution. Storm chasers travel in "crews" that move from state to state. They lack a permanent physical office in Miami, making it impossible to hold them accountable for warranty issues six months down the line.

    2. The "Free Roof" or "Deductible Waiver" Pitch

    This is the most common scam in Florida. A contractor tells you they can "waive your deductible" or give you a "free roof" by over-billing your insurance company. This is insurance fraud. In Florida, it is illegal for a contractor to pay, waive, or rebate any part of a property insurance deductible. If they are willing to cheat the insurance company, they are willing to cheat you.

    3. High-Pressure "Today Only" Pricing

    "I have a crew in the neighborhood right now, and if you sign today, I can give you 20% off." This is a classic tactic designed to stop you from doing your homework. A reputable Miami roofer will provide a detailed written estimate and give you time to review it.

    4. Lack of Miami-Dade NOA Knowledge

    In Miami, every roofing component: from the shingles to the nails: must have a "Notice of Acceptance" (NOA) from Miami-Dade County. If a contractor can't explain how they will meet High-Velocity Hurricane Zone (HVHZ) requirements, they aren't local experts.

    5. Demanding Large Upfront Deposits

    While a small deposit (10–15%) is standard to get on the schedule, a contractor asking for 50% or more upfront is a major red flag. They may use your money to finish a job in the last city they visited, or simply disappear.

    A professional Miami roofing crew installing hurricane-rated architectural shingles with precision, showing the proper use of underlayment and starter strips.

    The Miami-Dade HVHZ Standard: Why Local Matters

    Miami is part of the High-Velocity Hurricane Zone (HVHZ). This means roofs here must be engineered to withstand wind speeds of 150+ mph. Hiring a contractor who typically works in the Midwest or even North Florida is risky because they may not be familiar with the specific fastening patterns and underlayment requirements unique to South Florida.

    When vetting a contractor, ask these three technical questions:

    • "Are you using 6-nail patterns for shingles as required by Miami-Dade code?" (Standard is often 4 nails elsewhere).
    • "Can you provide the NOA numbers for the materials you’re using?"
    • "Will you be pulling the permit yourself, or are you asking me to do it?" (Never pull the permit yourself; it makes you liable for their mistakes).

    Real Data: What Should a Miami Roof Actually Cost?

    Transparency is the best defense against being overcharged. At Get My Roof Estimate Now, we use satellite technology to provide homeowners with accurate price ranges before they ever talk to a salesman.

    Based on current 2026 data for the Miami area, here are the typical price ranges for a standard 2,000 sq. ft. roof:

    Tier Material Type Estimated Cost (Miami, FL)
    Budget 3-Tab Shingles (Basic) $10,000 – $14,000
    Popular Architectural Shingles (Hurricane-Rated) $15,000 – $19,000
    Premium Concrete Tile or Designer Metal $24,000 – $28,000+

    Note: These ranges factor in the higher cost of Miami-Dade compliant materials and labor.

    A homeowner using a smartphone to view a satellite-powered roof estimate, showcasing the 60-second process of getting accurate roofing data.

    How Technology Levels the Playing Field

    The traditional way to get a roof estimate involved waiting three days for a contractor to show up, climb your roof, and give you a handwritten quote that might change later. This "wait and see" approach gives storm chasers the upper hand.

    By using satellite-powered measurement tools, you can:

    1. Get an "Unbiased Benchmark": Know the square footage and complexity of your roof (pitch, valleys, peaks) with 95% accuracy before a contractor arrives.
    2. Verify Material Costs: Our tool factors in the regional price differences for Miami, so you know if a contractor's "storm price" is actually a $5,000 markup.
    3. Skip the Pressure: You get the data in 60 seconds without having a salesman sitting at your kitchen table.

    The Miami Contractor Vetting Checklist

    Before you sign any contract in South Florida, run through this list:

    • Verify the License: Visit the Florida Department of Business and Professional Regulation (DBPR) and search by the contractor's name or license number.
    • Check General Liability & Workers' Comp: Ask for a certificate of insurance (COI) sent directly from their insurance agent to you.
    • Physical Office Location: Google the address. Is it a real office in Miami-Dade or Broward, or is it a UPS Store or a vacant lot?
    • Read Recent Reviews: Look for local reviews from the last 6 months. Be wary of a company with 1,000 reviews but none in the Miami area.
    • Get Your Own Estimate First: Use our Florida Roof Estimate tool to establish your budget benchmark.

    A modern Miami ranch home featuring a light-colored standing seam metal roof, designed for maximum energy efficiency and hurricane resistance.

    Final Thoughts: Protecting Your Investment

    Your roof is the most important component of your home’s defense system. In Miami, a poorly installed roof isn't just a nuisance; it’s a liability that could lead to catastrophic failure during a tropical storm.

    Don't let the urgency of a post-storm environment cloud your judgment. By leveraging technology to get an instant, accurate estimate and following a strict vetting process, you can ensure that your home is protected by a legitimate, local professional: not a transient storm chaser.

    Ready to see what your new roof should cost?
    Get your instant Miami roof estimate in 60 seconds here.